
Amex
- Rating
- 4.8
- Downloads
- 10.00M
- Content Rating
- Everyone
Amex - Screenshots
Amex - Description
- App Name
- Amex
- Package Name
- com.americanexpress.android.acctsvcs.us
- Developer
- American Express
- Category
- Finance
- Last Updated
- Dec 2, 2010
- Version
- 7.32.2
Analysis by TrendiApps
Managing an American Express account from a phone sounds simple, but the real test is what happens during an ordinary week: checking whether a purchase has posted, making a payment before a busy evening, or confirming that a reward balance is still available. I spent time using Amex as a mobile finance tool, and I found that its strongest quality is focus. It is built around the relationship between you and your American Express account rather than trying to become a general-purpose household budgeting app.
That focus makes it useful for cardholders who want quick account access without opening a browser every time. It also creates important boundaries for shared devices and family use. The app is free, comes from American Express, and is rated for Everyone, but that does not mean it is automatically suitable for every person in a household to use independently. Finance apps require clearer account ownership and more careful privacy habits than a shared shopping or entertainment app.
How Amex fits into everyday household use
A realistic example is a couple sharing responsibility for weekly expenses. One person may use the American Express card for groceries and fuel, while the other handles the payment. With the app, the cardholder can check the current balance and pass along the amount that needs attention without waiting to get home to a computer. If a reward balance is relevant to a planned purchase, it can also be checked from the same account area.
That convenience is most valuable when the phone is already in your hand. I found it easier to make a quick check after a purchase than to reconstruct spending later from memory. The app is also useful when you are away from home and need to confirm whether a payment has been made or whether an account detail looks right before making another decision.
However, I would not treat it as a shared household dashboard. The account belongs to the American Express customer who signs in, and the app is designed around that account relationship. A partner, parent, or roommate may help coordinate payments, but that does not turn the app into a neutral place where several people can safely browse one another’s financial information.
This distinction matters on a family tablet or a phone that several people use. Leaving an account signed in may be convenient, but it can expose balances, payment activity, rewards information, and other private details to the next person who opens the app. I recommend using a personal device whenever possible and signing out or securing the device when shared use cannot be avoided.
What I actually use it for
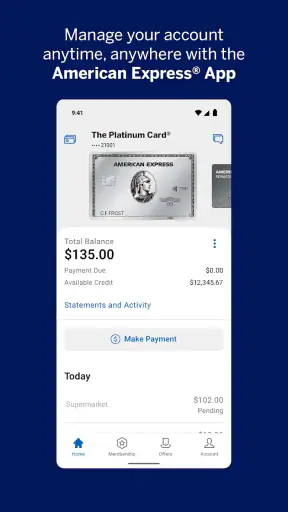
The main tasks are straightforward: viewing the account balance, making payments, and checking or redeeming rewards. Those functions cover the moments when a cardholder usually needs access most urgently. Instead of treating the app as a place to explore, I see it as a control panel for keeping an American Express account current.
Stories You Might Enjoy
Gallery’s Quiet Advantage: It’s Already Where Your Photos Live
Universal TV Remote Control Gets the Basics Right, but Setup Needs Work
Instagram’s Real Advantage Is Keeping Every Kind of Attention in One Place
Shadow Fight 3 Makes Every Duel a Lesson in Timing
Pizza Ready! Makes the Dinner Rush Feel Good—Until It Doesn’t
AliExpress Makes Curiosity Shopping Worth the Search
One useful habit is checking the account before a planned payment rather than relying only on a notification or a paper statement. That gives me a chance to review the situation in context and decide whether the payment should be made immediately. I also prefer checking the account after a significant purchase, because catching an unexpected item early is easier than sorting through a long history later.
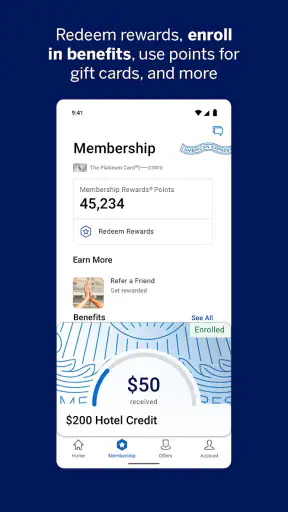
Rewards are another area where timing matters. I would not redeem points simply because the option is visible. I first consider whether the redemption fits the purchase I already intend to make and whether using rewards now is better than keeping them available. The app makes the balance and redemption area accessible, but the judgment about value still belongs to the user.
The app is not a replacement for a full household budget. If you need to combine rent, utilities, cash spending, several banks, and multiple cards in one plan, a dedicated budgeting service or spreadsheet may be more suitable. Amex is better when the question is specifically, “What is happening with this American Express account right now?”
Setting up boundaries on a shared device
The first boundary is simple: the person whose account it is should be the one who signs in and manages access. I would avoid handing an unlocked phone to another household member while the account screen is open. Even when everyone in the home trusts one another, privacy can be lost accidentally through a notification preview, an open screen, or a forgotten session.
A second boundary is deciding who is allowed to perform a payment. Helping someone read a balance is different from authorizing a financial action. In a household, it is sensible to agree that the account holder reviews the amount and confirms the payment personally, even if another person reminds them to do it.
This arrangement prevents a common source of confusion: one person assumes a payment was completed because another person opened the app, while the account holder assumes the opposite. The app can support coordination, but it cannot replace a clear household agreement about responsibility.
I would also keep account credentials out of shared notes, group chats, or casual messages. A shared device is already a point of exposure, and copying sign-in details into places designed for general household information makes the boundary weaker. The safest routine is for the account holder to enter credentials privately and keep the phone protected with its normal device security.
For a family that shares one tablet, the practical answer may be to use the app only when the account holder is present and then close the session. That is less convenient than leaving it ready, but the small inconvenience is reasonable for financial information. The app’s convenience should not encourage a household to treat a credit account like a shared media profile.
Coordinating payments without losing responsibility
Amex works well as part of a simple two-person routine. One person can be responsible for reviewing activity, while another can remind them about the payment date or transfer money into the appropriate household account. The important part is keeping the final action with the person who owns the American Express login and understands the account.
I like this division because it avoids pretending that the app is a collaborative finance workspace. A partner does not need unrestricted access just to help remember a payment. A short conversation can cover the amount, the timing, and who will handle it, while the account holder uses the app privately.
For shared spending, I would review purchases in batches rather than interrupting the other person after every transaction. For example, after a grocery trip and a household purchase, the cardholder can open the app, check the activity, and discuss anything that needs to be divided. This makes the app part of a repeatable routine instead of turning every purchase into a separate administrative task.
There is also a useful separation between account monitoring and rewards decisions. A household may agree that one person pays the bill while another suggests how rewards could be used. I would still have the cardholder make the final redemption choice, because rewards are tied to the account and may affect future plans. This is a small but important boundary when several people benefit from the same card.
Compared with checking the account through a mobile browser, the dedicated app feels better suited to quick checks. It keeps the account experience in one place and reduces the temptation to leave several browser tabs open on a shared computer. Compared with a banking app that aggregates many institutions, it is narrower: it gives a more direct American Express experience, but it does not serve as a complete picture of every account in the household.
Age, trust, and who should use it
The Everyone age rating makes the app broadly accessible from a content-classification perspective, but I would not interpret that as a recommendation for unsupervised financial use by children. A young person may be able to understand the screens, yet still lack the context to judge payments, balances, or rewards. The more important question is not whether someone can open the app, but whether they should have access to the account.
For teenagers learning about household money, a parent could demonstrate the app while keeping the sign-in and payment decisions private. Showing how a balance is reviewed or explaining why a payment is scheduled can be educational without turning the child into an account operator. Trust should grow through conversation and responsibility, not through casually sharing credentials.
For adult partners, the situation depends on the household’s financial arrangement. Some couples manage everything together, while others keep accounts separate. Amex can support either approach, but it does not remove the need to agree on privacy. If both people need independent access or separate responsibility, they should use the account arrangements available to them rather than relying on one person’s open session.
On a device used by several generations, I would be especially careful with saved access and visible notifications. An older relative may need help navigating the app, while a child may use the same phone for games or schoolwork. Assistance is fine; unattended access is a different matter. The account holder should remain in control of when the app is opened and what actions are taken.
Trust is also about reviewing information calmly. If a household member notices a purchase they do not recognize, the app can help bring the issue to attention, but the family should avoid jumping straight to blame. First identify whether it is a delayed posting, a familiar merchant under an unexpected name, or genuinely unfamiliar activity. The app is useful for seeing the account; good household communication is still needed to interpret what appears there.
Version, maturity, and day-to-day feel
The current version is 7.32.2, and the overall experience feels like a mature account-management product rather than a novelty finance tool. American Express has offered the app since December 2, 2010, which helps explain why the core workflow is familiar: sign in, inspect the account, act when necessary, and return later to verify the result.
Its scale is also clear. The app has passed ten million installs, with an average rating of 4.8 from around one hundred thousand ratings and roughly fifteen thousand written reviews. Those figures suggest that the basic experience works for a large audience, although popularity should not be confused with a guarantee that every device, account situation, or household routine will feel equally convenient.
I would expect the app to be most comfortable for an existing American Express customer who wants direct mobile access. Someone comparing cards or trying to manage finances before becoming an American Express customer may find less value in it, because its usefulness depends on having an account relationship to manage.
The free price removes a barrier to trying it, but the real cost is attention. A finance app is only helpful if the user checks it intentionally and understands what they are doing. Installing it will not automatically improve payment habits, and rewards can encourage unnecessary activity if they become the focus instead of a secondary benefit.
Where it is strong and where another option wins
My favorite aspect is the directness. When I want to check an American Express balance, make a payment, or look at rewards, I do not need a broad financial planning system around that task. The app keeps the relevant account actions close together, which suits people who already know what they need to do.
It is also a better fit than a shared spreadsheet for immediate account status. A spreadsheet can record household decisions, but it depends on manual updates and may quickly become outdated. Amex is the place I would use to inspect the account itself, while a spreadsheet or budgeting app could remain useful for dividing costs and planning future spending.
A mobile browser may be preferable for someone who rarely uses the account and does not want another app installed. A full banking app may be preferable for someone who wants checking, savings, loans, and cards in one overview. A dedicated budgeting tool may be preferable for households that need category limits, combined account tracking, or long-term planning. Choosing one of those alternatives is not a criticism of Amex; it simply reflects a different job.
The main friction is the narrow scope. The app can help you handle the American Express side of your finances, but it will not become the household’s complete financial command center. Shared-device use is another limitation in practice. The app may be easy to open, yet safe household use requires discipline around sessions, credentials, and who confirms actions.
I would also avoid using the app as the only record of a household agreement. If two people split a purchase, write down the arrangement somewhere appropriate or discuss it clearly. The account view can show activity, but it cannot know whether a charge was personal, shared, reimbursable, or part of a planned family expense.
Small routines that make it more useful
My first recommendation is to separate three moments: checking, deciding, and confirming. Open the app to see what is happening, pause to decide what action makes sense, and then return later to confirm that the intended action is reflected. This is more reliable than tapping through quickly while distracted.
Second, use a household reminder that names the responsible person rather than simply saying “pay the card.” That wording prevents the common problem where everyone assumes someone else handled it. The app provides the action, but the reminder provides the coordination.
Third, review rewards only when there is a real plan for them. If a household is saving rewards for a particular purpose, discussing that goal before opening the redemption area can prevent impulsive use. The app makes redemption accessible; a family rule determines whether the timing is sensible.
Fourth, make shared-device access temporary. Open the account, complete the necessary review, and close the session before handing the phone to someone else. This is especially important when the device moves between adult and child users. Convenience should never depend on everyone remembering not to look.
Finally, use the app for account-specific truth and another tool for household interpretation. Amex can tell the cardholder what is happening on the account, while a budget or shared note can explain who owes what and why. Keeping those roles separate makes both systems easier to understand.
My household verdict
I recommend Amex to American Express cardholders who want a focused way to view balances, make payments, and manage rewards from a phone. It is free, familiar, and direct, and its strong rating and large install base reflect how well that basic purpose serves many users. I especially like it for a person who wants to handle account checks between errands instead of waiting for access to a desktop.
For households, my recommendation comes with a clear condition: use it as an account-holder tool, not as an unrestricted shared finance space. Partners can coordinate reminders and discuss spending, but the person who owns the account should control sign-in and financial actions. On a shared device, temporary supervised access is safer than leaving the account open.
I would choose a broader banking or budgeting app when the main goal is seeing several institutions together, planning household categories, or assigning expenses across multiple people. I would choose Amex when the immediate need is managing an American Express account with as little friction as possible.
In the end, Amex is strongest when clear account ownership meets quick mobile access. It does not solve every household finance problem, and it should not be treated like a family profile with casual shared access. Used within sensible boundaries, though, it gives cardholders a practical way to stay informed, make timely decisions, and keep everyday coordination from becoming a last-minute scramble.
Amex FAQ
What is the Amex app used for?
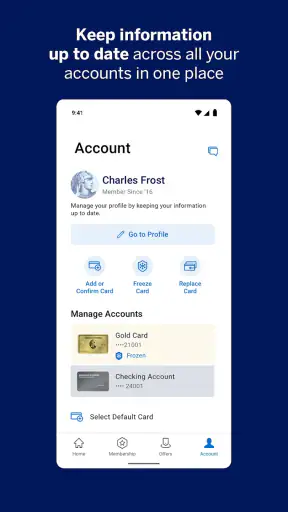
The Amex app is designed for American Express cardmembers who want to manage their accounts from an Android or iOS device. After signing in, you can review recent transactions, check your available credit, make payments, view statements, monitor rewards, receive account alerts, and access selected card benefits. The exact tools available may vary depending on your card, country, and account status.
Is the Amex app safe to use for payments and account management?
The Amex app includes security features intended to protect your account, such as encrypted connections, secure sign-in, account alerts, and options that may include biometric authentication on compatible devices. Even so, users should download it only from the official Google Play Store or Apple App Store, keep the operating system updated, avoid sharing login details, and use a private, trusted network whenever accessing sensitive financial information.
Can I make payments and manage my Amex card through the app?
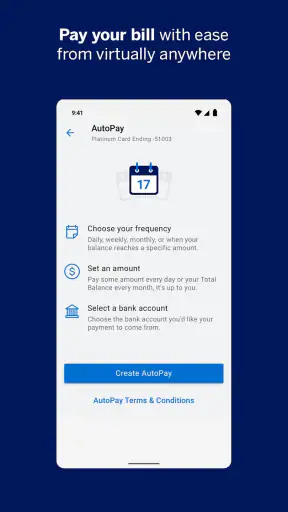
Yes, eligible cardmembers can generally use the Amex app to make payments, review payment due dates, see minimum payment information, and inspect payment history. Depending on the account and market, the app may also support scheduled payments, bank-account management, and payment reminders. Before confirming a payment, carefully check the selected funding account, amount, and processing date to avoid mistakes or delays.
Does the Amex app show rewards, offers, and card benefits?
The app can provide access to rewards information and selected benefits associated with your American Express card. You may be able to check your points balance, review eligible redemption options, activate merchant offers, and explore travel or purchase-related benefits. Availability differs considerably between cards and regions, so the app should be treated as a convenient overview rather than a guarantee that every benefit is available on your account.
What should I do if the Amex app is not working or I cannot sign in?
If the app fails to open, loads slowly, or rejects your sign-in, first check your internet connection and confirm that you are using the latest version from the official app store. Restarting the device or reinstalling the app may help, although you should know your login details first. For locked accounts, verification problems, or payment concerns, contact American Express through the official support options rather than unofficial websites or messages.
Pros
- Easy access to card details
- transactions
- and payment due dates.
- Useful purchase alerts help monitor spending and detect unusual activity.
- Secure login options include biometrics on supported devices.
- Digital wallet support makes eligible cards convenient for mobile payments.
- Travel features can help manage benefits
- offers
- and trip-related services.
Cons
- Many features require an eligible American Express card and account.
- Some benefits vary significantly by card type
- country
- and membership tier.
- The app may promote card offers that are not relevant to every user.
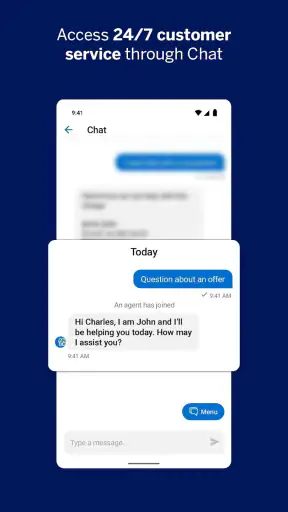
- Certain support requests may still require contacting customer service directly.
- Frequent updates and security checks can occasionally interrupt access.


